
Businesses rely on QuickBooks data to understand their financial position, create forecasts, and prepare their taxes accurately.
Without enough QuickBooks experience, business owners often make mistakes (including neglecting their books) that compromise the integrity of their QuickBooks files and leave them with inaccurate financial data.
That’s why they’re always looking for bookkeepers to straighten out their QuickBooks data, and why these projects have become so profitable. In fact, QuickBooks cleanup drove the most profits for accounting and bookkeeping firms in 2023.
Knowing how to bring order and clarity to the chaos in a client’s QuickBooks file will help you earn more from cleanup work. This article walks you through how to complete QuickBooks cleanups, so you can handle your next project with confidence.
What Is QuickBooks Cleanup?
QuickBooks cleanup is the review of a client’s financial transactions to fix errors and make their books complete, accurate, and tax-ready.
Common errors include missing or duplicate entries, and they’re most often seen when the foundation of the file was set up incorrectly.
At the end of a cleanup, the business’s financial data represents its finances accurately, which gives the owner the confidence to manage resources and grow the business. (If you clean up books outside QuickBooks too, see our broader bookkeeping clean-up checklist.)
Getting Set for a QuickBooks Cleanup
a. Get a signed engagement letter (and upfront payment) from the client
A signed engagement letter marks the beginning of your QuickBooks cleanup project. Engagement letters clarify the conditions of service, such as roles, responsibilities, payment, deliverables, and timelines.
Starting cleanup work without agreeing on these is unprofessional and can set you up for regrettable outcomes. Similarly, an upfront payment shows the client is committed to fulfilling their part of the bargain.
b. Back up the client’s QuickBooks data before starting
A backup protects your client’s QuickBooks data before the cleanup begins and provides a record of its state before your work.
The client’s historical data can also help you understand the context of their financial reporting and compliance requirements.
c. Gather all necessary documents before starting
Completeness, a primary goal of QuickBooks cleanup, is only possible with access to all the relevant documents. Veronica Wasek of 5 Minute Bookkeeping sees cleanup as a puzzle: you need all the pieces to finish it.
A thorough cleanup depends on access to all necessary documents and information, including bank statements, credit card statements, receipts, prior year-end records, bank deposits, and the last tax return.
You should also get access to the client’s QuickBooks account and an introduction to their tax preparer, if you’ll need to work with them at some point. Any document or information you don’t have upfront can cause delays later.
Download our free QuickBooks Cleanup Checklist Template
Steps to Perform a Comprehensive QuickBooks Cleanup
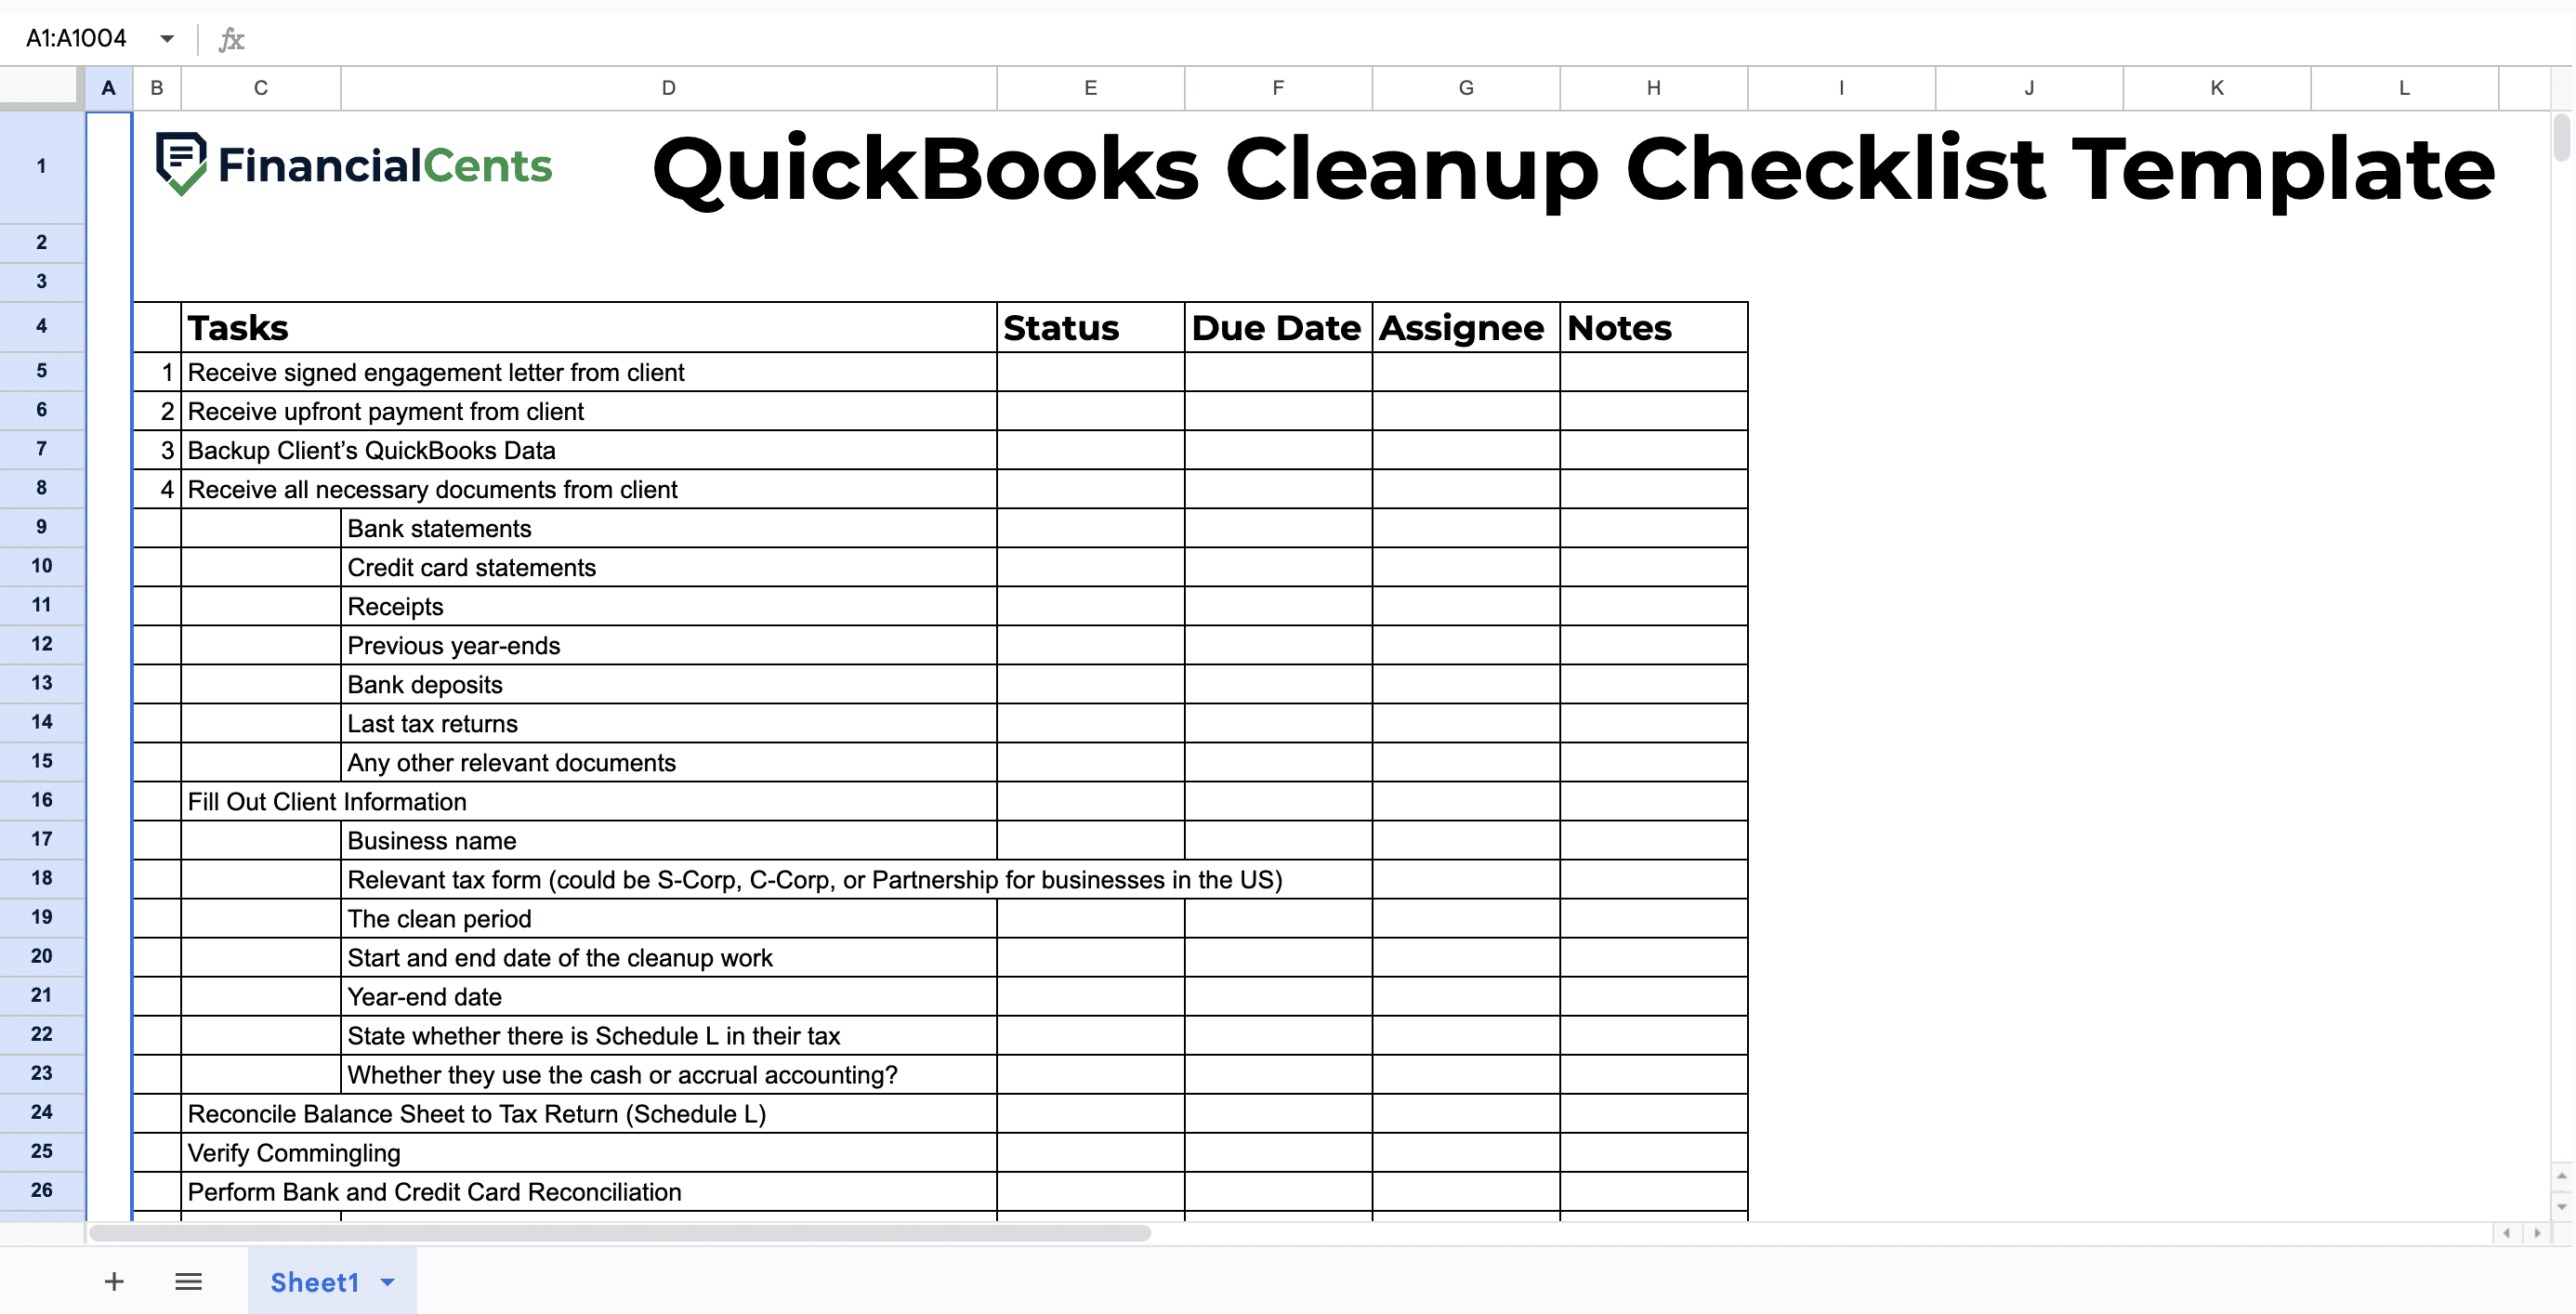
Here’s a general workflow for completing a QuickBooks cleanup, based on insights from Veronica Wasek of 5 Minute Bookkeeping. Diagnose your client’s QuickBooks file first to understand their issues, and tailor the steps accordingly.
a. Fill out client information
Start your cleanup by recording client information like:
- Business name.
- Relevant tax form (for US businesses, this could be S-Corp, C-Corp, or Partnership).
- The cleanup period.
- Start and end dates of the cleanup work.
- Year-end date.
- Whether their tax return includes Schedule L.
- Whether they use cash or accrual accounting.
b. Reconcile the balance sheet to the tax return (Schedule L)
Once you’ve documented the client’s information, reconcile the balance sheet to the tax return (Schedule L). This applies only to S-Corporations, C-Corporations, and partnerships. To do this:
- Check the client’s last tax return for Schedule L.
- If there is a Schedule L, reconcile the balance sheet in QBO with the balance sheet in the tax return.
- The two balance sheets should match. If they don’t, review your opening balances for adjustments.
- Bear in mind that the balance sheet on the last tax return might be incorrect. In that case, you may need to contact the tax preparer to resolve the discrepancy.
c. Check for commingling
This step shows the extent to which personal and business expenses are mixed in the client’s QuickBooks file, if at all. Find out whether the client’s personal expenses or accounts are in their QBO file and decide how they’ll be reported.
The goal is to remove personal expenses. They shouldn’t be in the QuickBooks file.
d. Verify transactions in QuickBooks and add missing information
Are all transactions recorded in QuickBooks? If not, import or enter the missing transactions to complete the books. You can also comb through the transactions in QBO’s bank feed.
e. Reconcile bank and credit card accounts
Bank and credit card reconciliation starts with making sure your opening balances are clean and accurate. Opening balances are the balance sheet balances (the client’s assets, liabilities, and equity) as of the end of the previous year or the last tax return.
Inaccurate opening balances will keep your bank and credit card accounts from reconciling, so address them first. A bank reconciliation template helps you work through each account consistently.
Address opening balances
- Were the bank and credit card balances in QuickBooks reconciled to statements in previous years? If not, do a catch-up reconciliation and note its date in the comments.
- Are there differences in the bank and credit card reconciliation opening balances? If so, adjust them.
Reconcile the current period
With opening balances addressed, reconcile the bank and credit card accounts:
- Adjust the beginning balances in the previous reconciliation to reflect your corrections to the opening balances.
- Prepare a monthly reconciliation for each bank and credit card account in the cleanup period.
- Review, then void or delete, old uncleared transactions, since they’re usually duplicates or errors.
- Keep old, uncleared payroll checks.
Balance sheet balances are cumulative, so errors only disappear once the books are cleaned up.
f. Clean up accounts at the transaction level
You may also need to clean up some accounts at the transaction level, such as undeposited funds, unapplied cash bill payments, and uncategorized assets and expenses. Cleaning these up ensures accurate opening balances on the balance sheet.
At the end of this cleanup, all transactions should be:
- Complete: all missing transactions are entered (bank feeds come in handy here).
- Categorized: transactions are moved to the appropriate accounts. You may need to work with your client to find out where certain transactions belong.
Pro tip: Cut the time your team spends on uncategorized transactions with Financial Cents’ month-end close feature. Instead of sending spreadsheets back and forth, it uses Financial Cents’ QuickBooks Online integration to ask clients about uncategorized transactions, remind them automatically, and categorize the transactions in QBO without leaving Financial Cents.
Other accounts to clean up at the transaction level
- Undeposited funds.
- Inventory: if the client uses QuickBooks inventory items, make adjustments.
- Accounts payable and receivable: make sure bills and invoices are cleared as they should be. You may need to write some of them off.
- Profit and loss: including income, expenses, and cost of goods sold.
g. Examine the chart of accounts
The chart of accounts shows a company’s historical trends and forms the basis of its forecasts. The goal here is two-fold:
- Examine each account for accurate entries and categorization.
- Make sure the chart of accounts supports the business’s operations and gives the owners the information they need to run the business efficiently.
Common chart of accounts errors include:
- Inconsistent naming: account names should follow one convention to prevent confusion.
- Too little (or too much) detail: accounts should be detailed enough to interpret easily, but not so granular they’re overwhelming.
- Outdated accounts: merge or archive them.
- Inactive accounts: mark them inactive, since they’re no longer relevant to the business.
- Duplicate accounts: merge them to prevent inflated figures.
- Misclassified transactions: move them to the appropriate account.
These fixes keep your client’s books in step with their evolving business.
h. Review and report
Review all accounts and reports, like the income statement and balance sheet, to make sure the client’s books are complete, accurate, and tax-ready.
Once you’ve confirmed every transaction and account is accurate, create a report for the client. It should state the scope of work, the accounts you worked on, the specific actions you took, your findings, and recommendations to keep their books healthy.
Best Practices and Tips for QuickBooks Cleanup
a. Document changes as you make them
Noting the changes you make to a client’s books gives you more control over the process. If you need to restore an account to its former state, you can do it more easily.
Done well, your notes become standard operating procedures for your team, and they make it easier to explain your changes to the client when needed.
b. Use a workflow or checklist template to streamline the process
Planning the flow of a QBO cleanup project can be challenging, from where to start to when the work is done. A cleanup checklist gives you an overview of the process and what you need at each stage.
Best of all, you don’t have to build one for every cleanup. Customize your existing checklist for each client based on the issues in their books.
c. Clean up data in smaller batches
Don’t try to do everything at once, especially on large cleanup projects. Work through the books in batches so you don’t get confused or overwhelmed. A checklist makes this easier, because you can focus on one task at a time as the project moves through its stages. For bigger jobs, a clean-up project plan and timeline helps you set milestones with the client.
d. Use workflow management software to track multiple cleanup projects
Most bookkeeping firms have several QuickBooks cleanups running at once. With so many moving parts in each, tracking them in a spreadsheet (or in your head) will overwhelm you and let things slip through the cracks.
Workflow management software takes on the job of storing information and remembering where each cleanup stands. It gives you a central hub for all work-related information, so you can focus on service quality and your firm’s growth.
Save Time on QuickBooks Cleanup Projects with Financial Cents
QuickBooks cleanups can be overwhelming. Each project means managing numerous transactions, chasing clients for missing information (unless you use the month-end close feature), and coordinating your team. You may even need to work with the client’s tax preparer, which makes staying organized harder.
With the right accounting workflow management software, you can store and manage all project and client information in one central place where your team can always find it.
Financial Cents, practice management software for bookkeepers and accountants, gives you a workflow dashboard to see where every project stands at a glance, an accounting CRM tool to keep track of client information, and other workflow management features to serve your QBO cleanup clients at scale.
Take Financial Cents for a spin. Start a free trial or book a demo.
The Financial Cents Editorial Team creates practical guides, templates, and resources for accounting, bookkeeping, and tax firms, drawing on our in-house experts and the firm owners we work with.
Share this article


Excellent article!